
Construction accounting tracks costs and income per project, and usually per job inside a project, instead of for the company as a whole. Costs arrive at different stages, revenue is recognised as milestones are reached, and the contracts behind each payment differ from one subcontractor to the next. This guide covers what makes it different from regular accounting, the methods and statements involved, how money actually moves through a project from estimate to final invoice, and how a small contractor sets it up without an ERP.
What is construction accounting?
Most companies run one general ledger for the whole business: money in, money out. A contractor with several clients needs to know the profit or loss on each project and, ideally, on each job within it. That is why construction accounting is project based, and why it is sometimes described simply as job costing.
Job costing works by attaching a project code, a cost code or both to every expense and every income entry, so you can see the balance for each. Most companies use a standard budget structure across projects so that jobs are comparable and easier to estimate next time. The budget estimate is that structure with the expected price and quantity for each job. Our budget template shows one example of such a structure.
In practice construction accounting requires three things: cost tracking per project for labour, materials and subcontractors; revenue recognition that follows how complete each project is; and job costing to see whether each project is making money.

How it differs from regular business accounting
Each project has its own duration, location, specification and set of contracts, so revenue, costs and cash flow are tracked separately for each one. Revenue is usually recognised against the percentage of the project completed rather than at the point of sale, which means someone has to track contract values, project phases and completion percentages. And the costs themselves split into direct costs such as labour, materials and equipment, and indirect costs such as overhead, administration and some insurance, both of which have to be tracked against the budget.
| Category | Product based accounting | Project based accounting |
|---|---|---|
| Production | Continuous, supporting ongoing business operations | Project based, each project accounted for separately |
| Location | Accountants working in the business department | Project managers doing the accounting on construction sites |
| Supply | Pool of strategic suppliers with standard terms | Specialised subcontractors and vendors with unique contracts and terms |
| Profitability | Company profitability across all revenue and expenses | Project specific, and hard to forecast |
| Cash flow | Continuous, stable and predictable | Uneven, changing with project stage |
| Contracts | Standardised, with simpler terms | Complex, with project specific terms and claims management |
Accounting methods used in construction
Percentage of completion
Revenue is recognised in line with how much of the project is complete, so income and expenses move together as work progresses. For long projects this keeps the books closer to reality. The drawback is that it depends on accurate progress tracking, which is where most of the effort goes. It suits larger projects where income needs to be matched to expenses over a long period.
Completed contract
Revenue is deferred until the whole project is finished. Simpler, and reasonable for short projects or where cost estimates are very uncertain, but it produces large swings in results from one year to the next.
Accrual and cash basis
Accrual accounting records revenue and expenses when they are incurred, whatever the cash position. Cash basis records them when money changes hands. Accrual gives the fuller picture and is needed for forecasting; cash basis is simpler for a small contractor with straightforward projects.
The financial statements
Three statements matter. The balance sheet shows assets and liabilities. The income statement shows revenue and expenses over a period, which is where profitable and unprofitable projects show up. The cash flow statement matters more in construction than in most industries, because payments often lag expenses by months.

How money moves through a project
The methods above describe how the books are kept. This is the sequence of documents that produce the numbers, which is what project managers and quantity surveyors deal with every week.
Estimate and bidding
The estimate is the starting budget. Before relying on it, you want evidence that the prices are realistic, either from price lists or by asking subcontractors for bids. The bids that come back become the first real forecast for the project. Once you accept a bid, you either sign a subcontract or send a purchase order for the materials.

Subcontracts and purchase orders
Knowing a project’s profit after it ends is already something. The harder part is checking, when a supplier or subcontractor invoices you, that you have not already received those materials or already paid that subcontractor in full. Purchase orders do that job for materials: you order a quantity, the supplier delivers against it, and the order is the document you compare the delivery and the invoice to. For jobs where the subcontractor supplies labour and materials, the subcontract fixes the quantities of work, and progress against those quantities is reported periodically, usually every two weeks or monthly, in progress reports.
Progress reports, pay applications, claims and valuations
Different countries use different names for the same document. The subcontractor submits it to confirm the work done. The project manager or quantity surveyor compares it against the contract, against what has actually been built, and against what was reported last time, then accepts or disputes it. Only once it is accepted can the subcontractor invoice for that work.

Change orders and variations
Work that was missed in design or added at the client’s request does not fit the original subcontract or purchase order. Autodesk describes a change order as “a bilateral agreement between parties to the contract”, and either side can raise one. Track change orders the same way as the contract itself: fix the agreed quantities and prices, and check them off in the progress reports, so the budget does not quietly grow past the estimate.
Invoices
The supplier bills you when the materials arrive, and the subcontractor bills you once you have accepted the progress report. The work is in receiving the invoices systematically and checking them with the people who know the project: find the contract or purchase order the invoice belongs to, check how much has already been paid on it, tell the accountant which account it posts to, then update the tracking spreadsheet so next month’s check is a little easier. Done by hand this takes days each month and adds nothing to the project. Our accounts payable guide covers how to set this flow up.
Work in progress (WIP) accounting
Work in progress, usually shortened to WIP, is the value of jobs that are underway but not yet invoiced in full. On a contractor’s balance sheet it shows up as an asset or a liability depending on which side of the gap the project sits. If the work completed is worth more than what has been billed, the difference is an asset usually called costs and earnings in excess of billings. If billing has run ahead of the work completed, the difference is a liability called billings in excess of costs, often shortened to overbilling.
Take a project with a contract value of £240,000. The team has spent £90,000 against an estimated total cost of £200,000, so the job is 45% complete by cost. At 45% complete, the earned revenue is £108,000. If the business has only invoiced £80,000 so far, it is underbilled by £28,000, and that £28,000 sits on the balance sheet as an asset until the next valuation catches up. If it had invoiced £130,000 instead, it would be overbilled by £22,000, a liability, because it has been paid for work it has not yet done.
A WIP schedule is usually one row per contract, updated monthly or at every valuation: contract value, cost to date, estimated cost to complete, percentage complete, earned revenue, amount billed to date, and the over or under billing figure that falls out of the other six. Pull the cost and billing figures from the same job costing records used for budget tracking, so the schedule does not drift from what the project team sees day to day.
Our glossary has a fuller breakdown of the WIP report, and our guide to construction in progress accounting works through the entries step by step.
Retention: receivable and payable
Retention is the slice of each valuation that a client or main contractor holds back until the work is signed off, usually between 5% and 10% of the certified value. A main contractor normally sits on both sides of it: retention it is owed by the client, and retention it owes to its own subcontractors. Keep the two as separate balances instead of netting them off, because they are released on different dates and the business needs to chase one while planning for the other.
Say a subcontractor’s valuation for the month comes to £60,000 and the contract sets retention at 5%. The client pays £57,000 and holds £3,000 as retention receivable. If the contractor’s own subcontractor valuation for the same period is £20,000 at the same 5% rate, the contractor pays £19,000 and holds £1,000 as retention payable. Tracked separately, the business can see it is net £2,000 ahead on retention for that month, which is easy to miss if the two figures live in separate spreadsheets.
Release is usually tied to practical completion and to the end of the defects or rectification period, and some contracts split it, releasing half at practical completion and the rest once the defects period ends. Build the expected release dates into the retention record when the valuation is first raised, because a date guessed on day one is often the only date anyone checks against months later.
Our guide to retention in construction covers how to track both balances and when they fall due.
CIS: the Construction Industry Scheme
Under the Construction Industry Scheme, a contractor deducts tax from payments to subcontractors and pays it to HMRC on their behalf, as an advance against the subcontractor’s own tax and National Insurance bill. The deduction rates are 20% for registered subcontractors, 30% for subcontractors who have not registered, and 0% for those with gross payment status (gov.uk, checked 7 October 2026).
Gross payment status lets a subcontractor collect the full invoice value with nothing deducted, provided it has paid its own tax on time, the business is run through a bank account, and its turnover from construction work over the last 12 months, ignoring VAT and materials, is at least £30,000 for a sole trader, or at least £30,000 per partner or director with a £100,000 minimum across the whole partnership or company (gov.uk, checked 7 October 2026).
Contractors file a CIS return every month, due by the 19th of the month after the one it covers, and must give each subcontractor a payment and deduction statement within 14 days of the tax month end (gov.uk, checked 7 October 2026).
Say a subcontractor invoices £5,000 for labour and materials, with £1,000 of that for materials bought directly. The deduction applies to the remaining £4,000. At the 20% rate that is £800, so the contractor pays £4,200 and sends £800 to HMRC. For the subcontractor, that £800 sits on the books as CIS suffered, an asset that reduces the tax bill at year end. For the contractor, it is a short-lived liability between the invoice and the monthly payment to HMRC.
For registration and the return itself, see our guides to what CIS is and how it works and filing the monthly CIS return.
VAT domestic reverse charge for construction services
The VAT domestic reverse charge for building and construction services has applied since 1 March 2021. Instead of the supplier charging VAT and the customer paying it over, the customer accounts for the VAT itself, as both output and input tax on the same return (gov.uk, checked 7 October 2026).
It applies when the customer is VAT and CIS registered, the service is standard or reduced rated, the supplier is not an employment business supplying staff, and the customer has not told the supplier in writing that it is an end user or an intermediary supplier that will not resupply the work. A main contractor whose client will not make a further onward supply of the construction service usually falls outside the charge once that end user notice is given, so ordinary VAT rules apply instead (gov.uk, checked 7 October 2026).
On an invoice that would otherwise carry VAT, the supplier leaves the VAT off, states the net amount, and notes that the reverse charge applies and the customer must account for the VAT. Say a subcontractor would normally invoice £10,000 plus £2,000 VAT for groundworks. Under the reverse charge it invoices £10,000 net, marked for reverse charge, and the contractor declares the £2,000 as both output and input VAT on its own return. The subcontractor never holds that £2,000, cash it used to keep for a few weeks between the invoice date and the VAT quarter it was due. For a subcontractor used to that float, the reverse charge takes away working cash it could previously rely on, even though the job itself has not changed.
Cost types and job costing
Direct costs are labour, including wages, benefits and subcontractor fees; materials and supplies; and equipment, whether owned and charged by the hour or day, or rented. Indirect costs are project overhead, office costs, utilities, insurance, telecommunications and taxes. Both sides have to be tracked against the budget, and accurate cost records are also what make the next bid competitive.
| Direct construction costs | Indirect construction costs |
|---|---|
| Labour costs | Project overhead costs |
| Material costs | Office costs |
| Equipment costs | Utilities |
| Construction tools and machinery | Insurance |
| Subcontractor costs | Telecommunications |
Job costing starts with a detailed estimate with line items for labour, materials and subcontracts, and then compares actual costs against it as invoices are approved. The comparison is only useful if it is current, which is the argument for software that updates the budget at the moment an invoice is approved rather than at month end. Planyard’s job costing works that way.

Cash flow
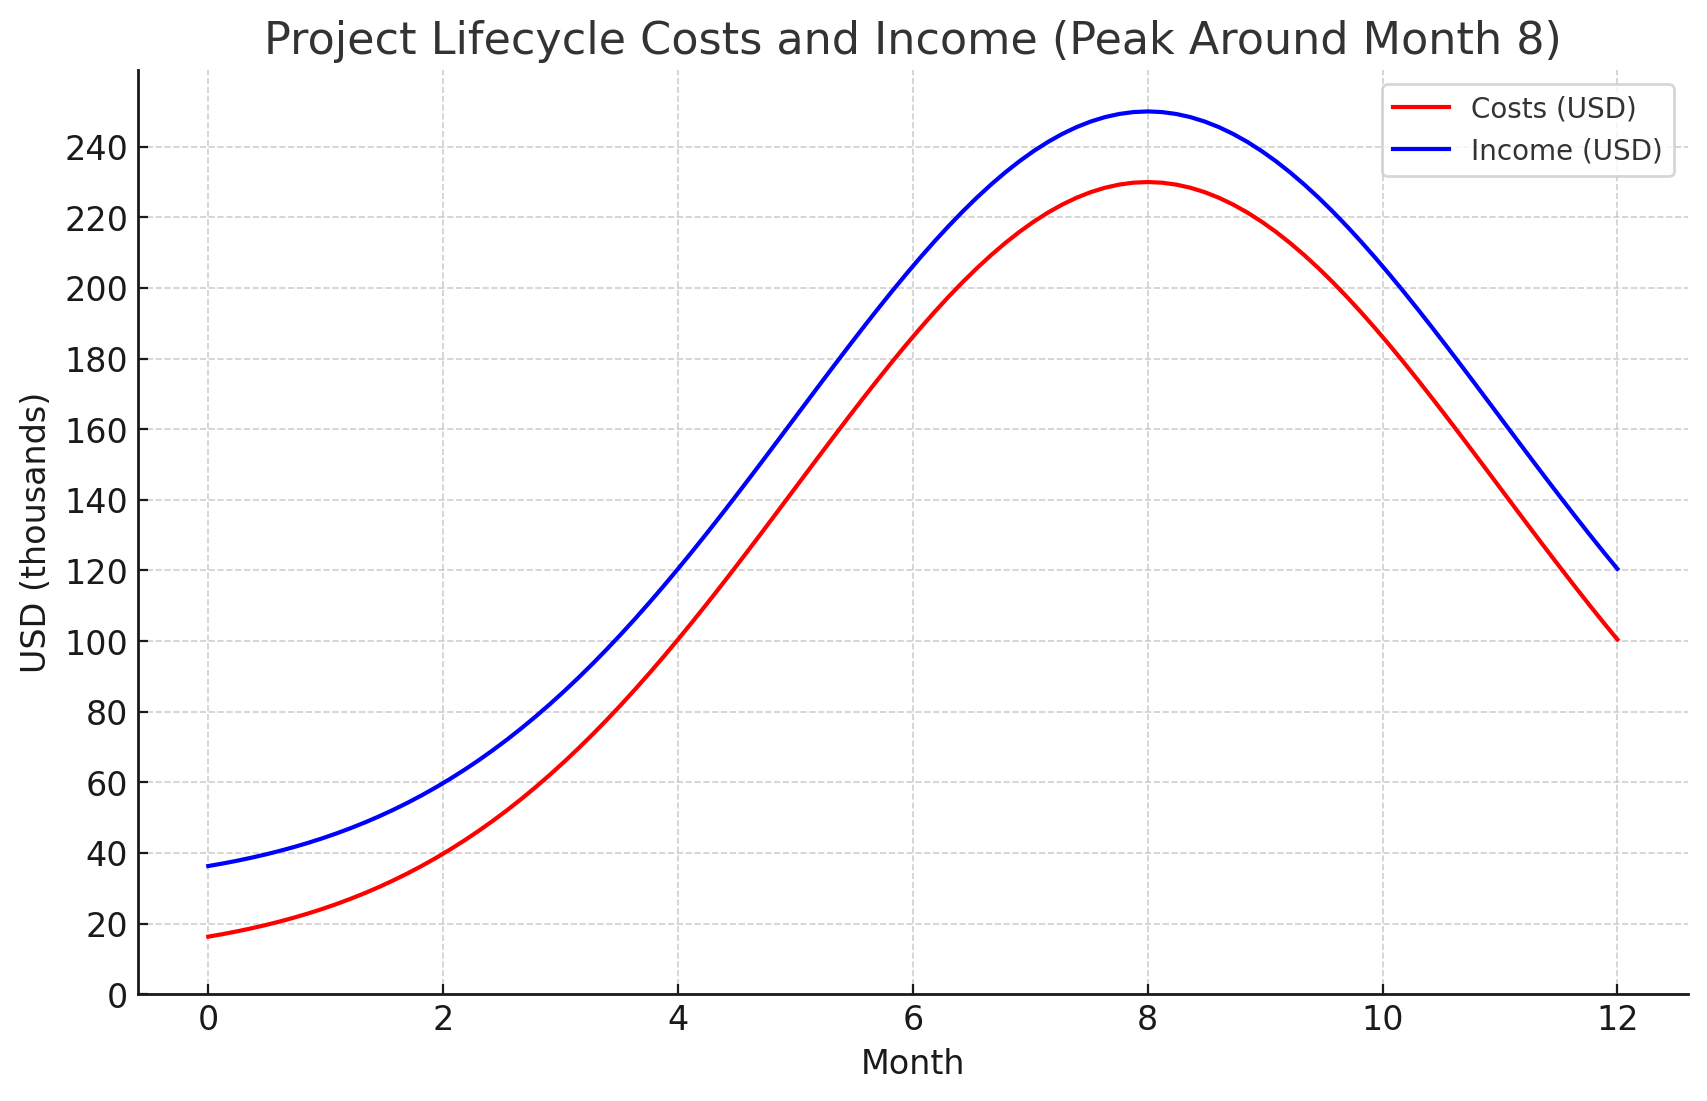
Cash flow is tighter than profitability for most contractors because payments are irregular and large expenses land early. Forecast it in two horizons: weekly and monthly needs in the short term, and an annual view for seasonality and large purchases. Structure contracts with milestone payments or a deposit at the start to cover early costs, and keep a reserve from project revenue for delays and surprises.
Three rules of thumb from contractors who keep projects cash positive: client payment terms shorter than supplier terms, so client money arrives before vendor money leaves; bill for more than you owe in every cycle; and watch out for the trap where clients have prepaid and projects are not finished, which looks like healthy cash and is not.
A cost control meeting with three numbers
You do not need fifty KPIs. Meet every two weeks or every month and look at three things per project: forecast profit and how it has moved since last time; project cash flow, with a task assigned to the project manager wherever the balance is about to go negative; and remaining costs, remaining income and remaining cash flow, which should also be positive. If preparing the month-end cost value reconciliation for that meeting takes project managers and quantity surveyors a day or two, the preparation is the problem, and a cost control tool brings it down to minutes.

Getting started as a small contractor
Growing contractors hit the same wall: cash flow nobody can see, budget overruns discovered when the invoice arrives, each project manager running a private spreadsheet, and three to five days a month lost re-entering the same numbers. Planyard has worked with thousands of businesses in Australia, the UK, the EU, the US and Canada, and the ones that got out of that state did it in roughly this order.
- Fix one problem first. Trying to solve everything at once is the usual failure. Pick one: project profitability and overruns, standardising processes before hiring, or the time the team spends on admin. Expand once that is stable.
- Outsource the accounting until forecasting and financing need someone in house. If the accountant’s job is tax reporting and payroll, an external service costs a fraction of a full-time hire, often under 10%. An in-house finance role pays off later, when forecasting, financing and investors need attention.
- Use Xero or QuickBooks, not an ERP. ERPs are built for companies with a hundred or more staff and take months to set up. A cloud accounting tool from around $29 a month will do, provided it supports invoice scanning, tracking by project and cost code, approval workflows and batch payments to the bank.
- Set up cost codes before the next project starts. Cost codes let you compare estimate against actual in real time, reuse live cost data in future estimates, and catch overruns while there is still time to act. Involve the project managers and quantity surveyors in defining them, or they will not use them. See the cost codes guide.
- Put all invoices through one inbox. A single accounts payable address for every supplier and subcontractor invoice, then a fixed route: the project manager or quantity surveyor assigns the invoice to a project and cost code, a manager approves it, the accountant books it and uploads the batch to the bank. The accounts payable guide goes through this step by step.
- Run the three-number meeting above. Forecast profit, cash flow and remaining position per project, every two weeks or every month.
Construction accounting software
Everything above can be run on Excel, Outlook and your accounting package, and for a smaller contractor with a few projects that is fine: keep the contracts in a shared folder, refer to them when you approve costs, and keep the process simple. Once projects run into the millions or tens of subcontractors are on site at the same time, the system starts to shake. The usual stopgaps are hiring quantity surveyors to do the data entry or giving up weekends to the month-end spreadsheet.
Construction accounting software such as Planyard or Procore moves the data entry to the subcontractors, who submit their own progress reports and invoices, and leaves the project team to check values against the contract and against what was approved before. Approved documents then go to the accounting package automatically. Planyard integrates with Xero, QuickBooks, MYOB and Sage, captures invoices and links them to budget lines, updates the project budget as each invoice is approved, and reports project profitability and cash flow from current data rather than last month’s. For a comparison of the options, see our list of the best construction accounting software.
If the accounts themselves still need setting up, our construction bookkeeping guide covers the chart of accounts and the basic records a small contractor needs before any software gets involved.

Summary
Construction accounting is harder to read than company accounting because every entry needs a project and job reference before it means anything. Keep that reference on every estimate line, order, progress report, change order and invoice, forecast cash flow rather than discovering it, and start with one process rather than all of them. If you are already finding cost tracking difficult, book a demo and we will show you how Planyard handles the flow above.